
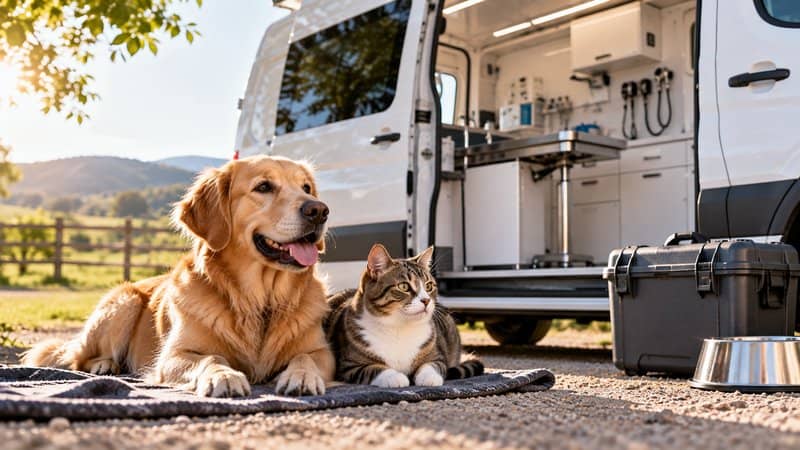

A mobile veterinary practice can help you build a business around a specific community or service. You might make house calls for dogs and cats in suburban neighborhoods, travel between farms and ranches to care for livestock, or serve multiple rural towns from one mobile clinic. Instead of waiting for clients to walk through your doors, you take your services directly to the animals that need them.
But turning that idea into a working business takes more than a good plan and veterinary expertise. You’ll need a reliable vehicle, medical equipment, supplies, fuel, and enough working capital to keep the practice running as you build your client base. That means small-business loan financing that fits how your mobile clinic will actually operate.
This guide walks you through what lenders look for when reviewing your application and highlights funding partners that can say yes to your dream.
Table of Contents
ToggleWhat Lenders Evaluate in Your Application
Lenders mitigate their risk by ensuring you can repay your loan before they offer you funding. They do this by closely reviewing your financial information and business history, though each lender weighs these categories differently.
You can typically expect to provide:
- Bank statements from the most recent three to six months
- Revenue records or profit-and-loss summaries
- Time-in-business documentation
- Basic business information
Time in business is a standard qualification. Lenders want to see if you have a history of successfully repaying loans, managing your income, paying your expenses, and turning a profit. The longer you’ve been in business, the better they can evaluate your financial history.
Most fintech lenders require six to 12 months of operating history, while traditional banks and Small Business Administration (SBA) lenders may require three to five years in business. Equipment financing companies may extend loans to newer practices or even start-ups when the financed vehicle or equipment serves as collateral.
Your credit score is another indicator of your financial history, which is why lenders evaluate your credit profile to approve a loan. Some rely more heavily on credit scores than others, though. Revenue-based lenders can often approve businesses with consistent cash flow even if they have limited credit history.
Overall, revenue and cash flow history carry the most weight, and your bank statements give lenders a real-time picture of how money moves through your business. Consistent monthly deposits, positive account balances, few overdrafts, and regular bill payments are strong indicators that you’ll have the funds to cover your payments.
Top Loan Companies for Mobile Vet Clinics
Mobile veterinary clinics can be harder to classify under traditional lending models. You operate from vehicles and serve a wider range of clients than a vet clinic in a fixed location. And you experience more significant seasonal revenue swings than traditional animal care centers.
Those characteristics make it harder for a traditional bank to approve your application. Standard underwriting processes lean on credit score, years in business, consistent revenue, and fixed collateral. It’s hard even for a financially healthy mobile practice to check every one of those boxes.
It’s typically easier to secure funding through fintech lenders. These providers rely more on cash flow trends that show responsible management and growing demand than on historical data. And because they frequently fund service-industry and seasonal businesses, these lenders can read a winter slowdown in context and offer products that work with your revenue cycle.
The following fintech lenders and online loan companies make top veterinary business loans accessible and provide the right kinds of products to get your mobile veterinary clinic on the road.
Biz2Credit
Biz2Credit is both a direct lender and a financing marketplace. You provide some basic information to create an account on their platform and prequalify. After you complete the online application and share your bank statements, you get official offers from Biz2Credit and its network of lenders within 24 hours. You can compare which products and terms will work best for your business in just a few minutes.1
Biz2Credit offers useful financing for vet practices. You can secure the vehicle and equipment you need using this lender’s term loan or equipment financing. To manage your working capital needs, Biz2Credit offers invoice financing, lines of credit, and revenue-based financing.2
Each product features different terms and qualifications. Biz2Credit’s term loan has some of the more strict criteria, requiring at least 12 months in business, a 650 credit score, and $100,000 in annual revenue. But their revenue-based financing is available to businesses with a credit score as low as 575 because Biz2Credit prioritizes cash flow.3
The advantage of a lending marketplace is that you can compare multiple options through a single application. If you’re not sure what you need for your mobile clinic or what you can qualify for, Biz2Credit can be a good place to start.
Cardiff
As a leading working capital firm for small businesses, Cardiff opens the door to businesses of all kinds. If your credit score is 550 or higher and you have at least 12 months in business, you can qualify for funding. Cardiff analyzes your real-time revenue and evaluates your overall financial health by connecting to your bank account via Plaid.4
This process can be very quick. You fill out one application for all of Cardiff’s products and get a decision in a matter of minutes. The lender then assigns you a dedicated rep, so you can have expert guidance choosing the financing that your practice needs. And you can often secure funding that same day.4
Cardiff’s range of financing products covers both equipment and operating needs for mobile veterinary practices. If you need financing for business equipment, you can choose between a loan or a lease. Working capital, invoice financing, business lines of credit, and merchant cash advances (MCAs) can cover cash flow gaps. Cardiff even offers products specifically for medical services that fit your business model.4
For ongoing flexibility, Cardiff allows you to choose between fixed and revenue-based repayments on a daily, weekly, or monthly schedule for most of its products. And Cardiff does not charge a prepayment penalty on its financing when you pay it off early.5 This allows your funding to move through the seasonal ups and downs without hurting your business.
Cardiff makes it easy to access funds for a mobile veterinary clinic, supports your efforts through a loan advisor and offers choices in products and repayment terms.
Credibly
Credibly publishes its qualification requirements, making it easier to understand what it looks for in working capital applicants. You must have at least six months in business, a credit score over 500, $15,000 in monthly revenue deposited into a bank account, and U.S.-based operations. If you meet those minimums, Credibly then uses your revenue data and business performance to approve loan amounts and borrowing rates.6
This lender has a faster turnaround than traditional lenders. Credibly’s online check-out system lets you apply for and finalize loans on your timeframe. A loan advisor will reach out to you about your approval in less than two hours, and you can often receive same-day funding.6
Credibly offers multiple financing products that can work for mobile veterinary clinics. You can use long-term business loans or equipment loans to set up your vehicle with the necessary tools and features. If your clinic needs a capital infusion before the busy season, you could secure Credibly’s line of credit, working capital loan, or MCA.6
If you want clarity on your application and financing terms from the start, Credibly is a practical place to begin.
National Funding
With its focus on financing service-industry businesses and equipment-heavy operations, National Funding offers underwriting and products that work for mobile veterinary clinics. This equipment financing company offers loans and leases for specialized assets, as well as working capital loans and receivables financing to meet cash flow needs.7
You apply online, with no impact on your credit score. National Funding will accept applications from any business and look at your whole financial profile during the underwriting. If your credit score is 600 or higher, you can typically qualify. After you apply, a funding specialist reaches out to you to tailor the terms to your situation. You can often secure the funds the day after you accept your financing.7
National Funding’s assigned advisors provide valuable experience to equipment-heavy service businesses. Your funding specialist can help you decide when to purchase or lease assets for your mobile clinic.7 It’s worth considering this lender for specialized and flexible equipment financing, especially.
Lendistry
As a preferred lender for Small Business Administration (SBA) loans, Lendistry provides long-term, low-cost financing for major expenses.8 You can secure up to $5 million through the SBA 7(a) Standard Loan with repayment terms up to 10 years.9 You may need that kind of financing when you’re outfitting a new mobile clinic or expanding to a fleet.
Lendistry uses a convenient online application to upload your tax returns and other documentation. Applying can take a little time because SBA loans come with strict underwriting requirements. If you have at least two years in business and a credit score of 620 or higher, you may qualify. You may wait anywhere from three to 90 days to receive your funds, though.9
With a financing program designed around the needs of veterinary businesses, Lendistry makes funds available through its conventional and SBA loans. You can finance the equipment and working capital your clinic needs with long repayment terms and low interest rates.10
Lendistry works best when you have an established practice and a clear plan for substantial capital to grow your fleet or expand into mobile vet services.
Match the Lender to Your Capital Needs
Whether you’re making house calls for dogs and cats or traveling to farms and ranches, financing can help turn your idea for a mobile veterinary practice into a working business. The key is finding a lender and funding option that fits what you need.
Each lender here addresses a different slice of a mobile vet clinic’s financing needs. A line of credit from Biz2Credit may make sense for ongoing expenses, or an equipment lease through Credibly could be a better fit for your vehicle. Or you might secure a combination of short and long-term products from Cardiff to meet all your capital needs through a single lender.
The best veterinary loan company is the one that approves your application and helps you secure the funding to make your dream a reality.
Sources:
1https://www.biz2credit.com/
2https://www.biz2credit.com/loans-for-doctors
3https://www.biz2credit.com/financing
4https://cardiff.co/
5https://cardiff.co/learn/faq/
6https://www.credibly.com/
7https://www.nationalfunding.com/
8https://lendistry.com/faqs/
9https://lendistry.com/
10https://lendistry.com/veterinary/