

Landscaping businesses live by the seasons. You’re aerating lawns, reseeding grass, installing pools, and generally preparing properties during the spring. Demand continues through the summer, but now you mow lawns, trim bushes, spray for pests, and remove weeds. Even as plant growth slows down in the fall and winter, you can stay busy installing outdoor kitchens, planting bulbs, and winterizing water features.
Each season also impacts the kind of financing you need. Just like an aerator won’t help you with leaf removal, a loan that helps you cover payroll during the winter months usually isn’t the right tool for investing in equipment. Managing the different capital challenges you face each season requires more than one type of financing.
Term Loans for Growth
Equipment carries your landscaping company, but it is also your biggest expense. A quality commercial mower can cost $10K even before you add trailers, trucks, leaf blowers, and other tools to the mix. The upfront investment grows quickly.
Rather than tying up your working capital by paying cash for these purchases, consider a small business equipment loan. With these term loans, you secure a lump sum to fund a major purchase. Then you repay the borrowed amount plus interest over monthly payments for a set period. The repayment term spreads the cost out over the life of the equipment, to allow the returns on your purchase to help pay for the financing.
Expanding your crew is another big purchase for landscaping businesses. You have to cover hiring costs, payroll, training, and onboarding before those employees contribute to revenue growth. With a term loan, you can pay these costs upfront and repay it with fixed monthly payments. As long as the payment schedule works with your seasonal income, you’ll have funds to add to your crew without draining your operations budget.
Working Capital for Seasonal Gaps
Your landscaping business may not see much action from December to February, but you still have to pay for insurance, vehicle maintenance, fuel, financing, and payroll for year-round staff. That’s when you may need more flexible access to cash than a term loan can provide.
A business line of credit is an adaptable working capital product. It gives you access to a pool of funds you can draw on as needed and only pay interest on what you use. The best business lines of credit feature revolving access. During a slow month, you might withdraw funds to cover payroll and materials. Then, as you repay the borrowed amount in the spring, each payment replenishes the funds you can draw on later.
Sometimes you need flexible repayments more than you need ongoing access to funds, like when you need to pay for repairs during the off-season. With a working capital loan, you secure the lump sum for cash, like with a term loan. But then you repay the borrowed amount through a portion of your revenue rather than in fixed payments. This means you pay less when demand for landscaping dies down and more when business picks back up.
Both working capital loans and business lines of credit offer the flexibility to cover expenses during the off-season and gear up for the growing season by matching landscaping’s natural revenue cycle.
Landscaping Business Loan Providers
Many different lenders offer business lines of credit and term loans that can work for your business. But the best landscaping business loans tailor to your business model. The following loan companies provide flexible financing for both major purchases and cash flow gaps that align with your seasonal revenue.
IOU Financial
IOU Financial connects small businesses to a range of financing products, both through direct funding and its network of preferred brokers. You apply with minimal documentation and generally need at least one year in business, $10K in monthly revenue, and a credit score of 630 or higher to qualify. Once approved, you connect with a dedicated advisor to discuss your options and can secure funding in as little as one day.1
For financing seasonal changes, IOU Financial offers business lines of credit for ongoing access to capital. Its term loans can also cover working capital needs. You can choose repayment terms between six months and two years with daily, weekly, or biweekly payments. And because you can secure between $15K and $1.5 million, IOU’s term loan can work for large, short-term investments as well.2
If you need more funds or longer terms to invest in your landscaping tools, consider IOU Financial’s equipment financing program. If you have more than two years in operations and a credit score higher than 650, you could secure up to $2 million through a loan or lease. You’d then repay the loan through fixed monthly payments for up to 84 months,3 giving your equipment time to generate a return.
Cardiff
If you’re looking for flexible and industry-specific loans, consider Cardiff. Cardiff connects you with a dedicated loan advisor once you apply, to help match you with the right financing and customize the terms for your landscaping business.4
You start by connecting your bank account via Plaid to apply for multiple products in less than five minutes. Cardiff approves applications on the strength of your real-time data, though if you have at least six months of operations history, $10K in monthly revenue, and a credit score higher than 550, you can qualify for most products.4
Cardiff offers revolving lines of credit and working capital loans for seasonal needs. The credit line auto-adjusts to your real-time business performance, so you have access to more funds as your company grows, as well as when you make payments.5 And with Cardiff’s working capital loans, you can secure up to $500K through the working capital loan, and choose between revenue-based or fixed daily, weekly, or monthly payments.6
Cardiff offers landscaping-specific terms, particularly for equipment financing. Payments toward your loan or lease can ramp up as the equipment generates revenue or align with your seasonal revenue. Cardiff can even defer payments for up to one year. These terms, plus the fact that you can fund 100% of your equipment costs for up to seven years, fit landscaping’s seasonal patterns.7
With its ongoing experience serving landscaping companies, Cardiff offers personalized flexibility on equipment financing, business lines of credit, and working capital loans. That is worth a look, especially since Cardiff can offer fast approvals and same-day funding, in many cases.4
SBG Funding
SBG Funding offers up to $10 million in funding with decisions in less than 24 hours, making it ideal for landscaping businesses that urgently need significant capital. You typically need six months in business, $250K in annual revenue, and a credit score of 500 or higher to qualify for SBG’s term loans, lines of credit, or equipment financing.8
SBG Funding primarily offers business lines of credit for working capital needs. The maximum credit limit for this product is $500K, and you receive the funds the same day your draw is approved. The available credit replenishes as you repay the borrowed funds, and you can request a credit increase through your funding specialist.11
To access the maximum amount of capital, start with a term loan. SBG Funding offers lump sums ranging from $5K to $10 million with six-month to four-year repayment terms. You could also use its equipment financing program to purchase expensive assets for your landscaping business, as SBG can fund up to 90% of the equipment’s value.10
When you face particularly expensive investments, SBG Funding offers the opportunity to secure the funds you need quickly. Partnering with this lender gives you a source for equipment and working capital problems.
Everything in Its Season
As a landscaper, you understand seasonal rhythms. You can adapt your services, tools, crew, and schedule to meet the distinct demands of summer, spring, fall, and winter. Selecting the right loan as your financing needs change extends your adaptability to another aspect of your business.
The key is matching the product to the job at hand. A line of credit can help you cover payroll and supplies while you wait for customer payments, while an equipment loan can help you replace a worn-out truck. By adapting your financing to fit your business’s needs throughout the year, you can keep your landscaping company running smoothly now and be ready for the next season.
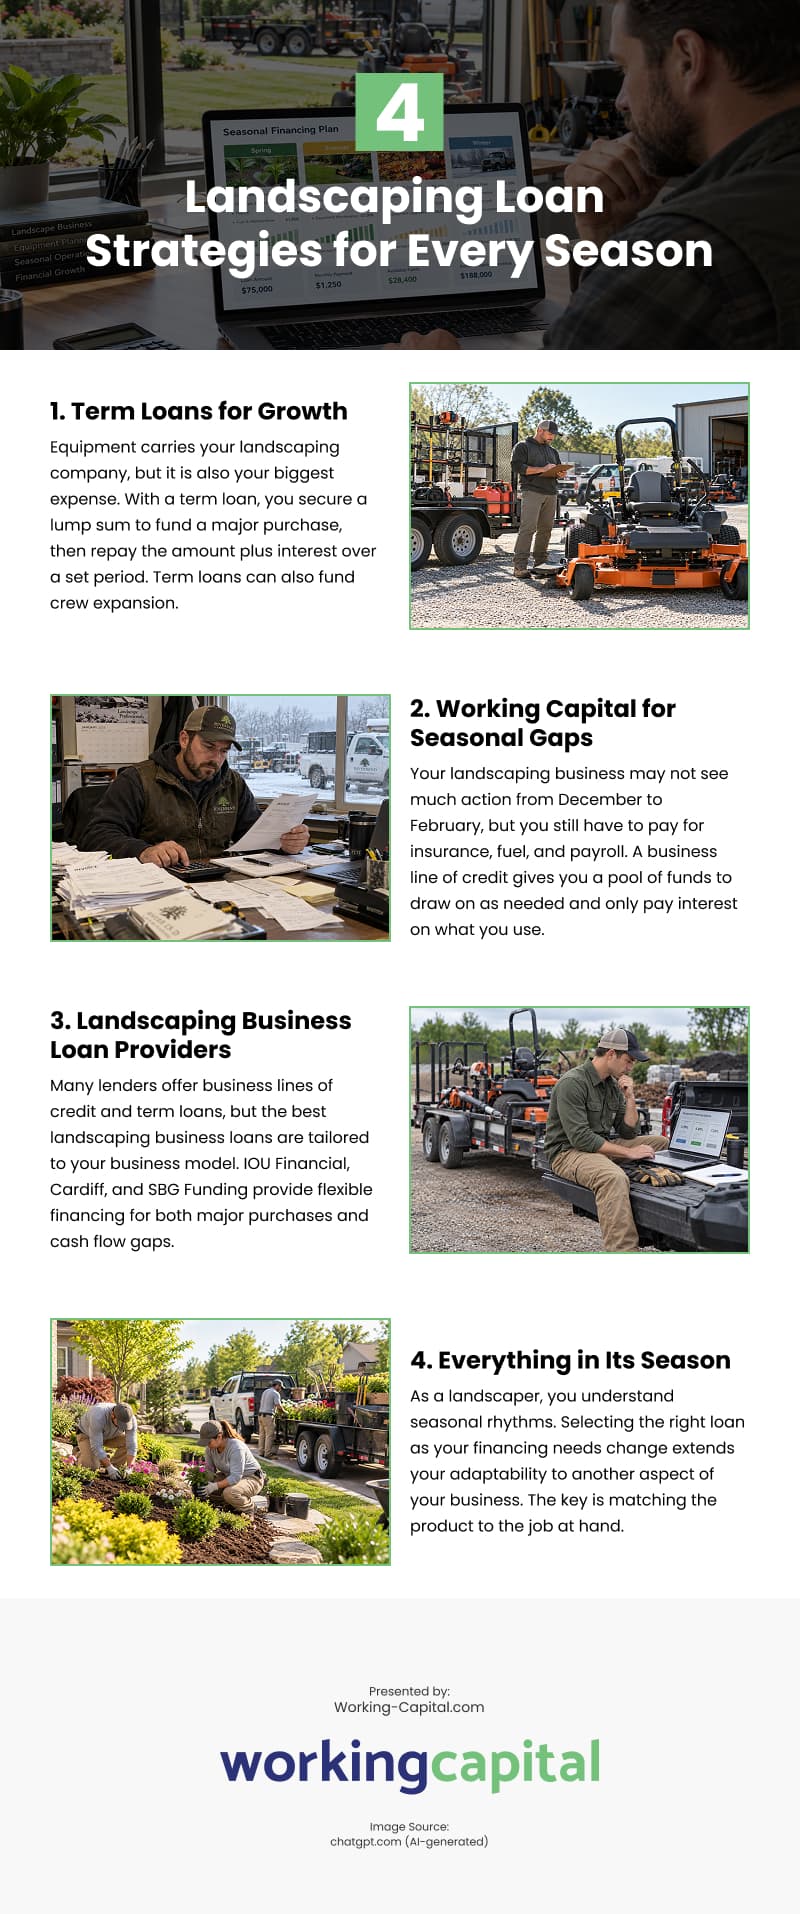
Infographic
Sources:
1https://ioufinancial.com/financing-options/business-line-of-credit/
2https://ioufinancial.com/financing-options/term-loans/
3https://ioufinancial.com/
4https://cardiff.co/industries/landscaping/
5https://cardiff.co/business-loans/products/line-of-credit/
6https://cardiff.co/business-loans/products/working-capital-loans/
7https://cardiff.co/business-loans/products/equipment-leasing/
8https://sbgfunding.com/
9https://sbgfunding.com/termloan/
10https://sbgfunding.com/business-financing/equipment-financing/
11https://sbgfunding.com/business-financing/business-line-of-credit/